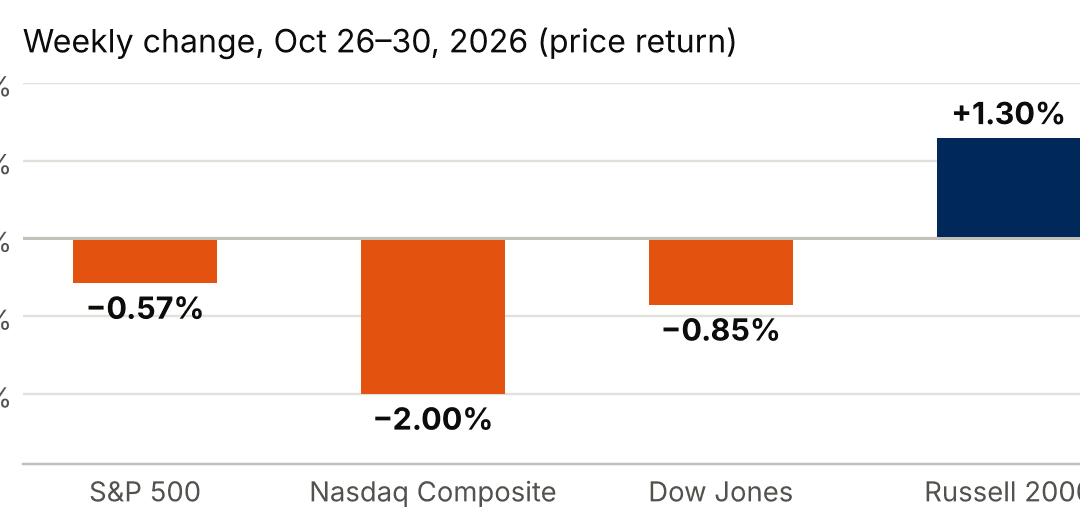
U.S. stocks climbed through Wednesday, then gave it all back. The S&P 500 slipped 0.6% and the Nasdaq fell 2.0%, each for a third straight weekly decline, and the Dow lost 0.9%. Small caps held up, with the Russell 2000 up 1.3%. The turn came after Alphabet and Amazon reported results that renewed doubts about the payoff from AI spending, and Intel’s warning sent its shares down nearly 29% on Friday. The Nasdaq fell 2.9% on Friday, its worst day since June 5.
- The Fed held, with two dissents for a hike. The policy rate stays at 3.75%–4.00% (10–2 vote). Traders price roughly a 76%–85% chance of a quarter-point hike on December 9.
- Big Tech spending drew a harsh verdict. Alphabet had its worst day in more than 20 years; Amazon’s trailing free cash flow turned to a record $42.4 billion outflow. Microsoft, helped by 48% Azure growth, held up.
- Strong growth, sticky inflation. Third-quarter GDP grew 3.4% annualized; September PCE inflation ran at 3.6% (core 3.1%).
- Oil stayed near its highs. WTI settled at $104.12 and Brent at $113.43 as tankers were struck in the Strait of Hormuz. Gold fell to a one-year low near $3,900.
- Yields fell. The 10-year Treasury yield ended near 4.93%, down about 7 basis points.

| Index | Friday close | Week | Friday | YTD |
|---|---|---|---|---|
| S&P 500 | 7,580.07 | −0.57% | −1.82% | +10.7% |
| Nasdaq Composite | 25,437.00 | −2.00% | −2.86% | +9.4% |
| Dow Jones | 51,770.31 | −0.85% | −1.09% | +7.7% |
| Russell 2000 | 2,811.84 | +1.30% | −1.66% | +13.3% |
Price returns. The S&P 500 and Nasdaq are 3.0% and 7.8% below their record closes of October 6.

The AI trade: the bill comes due
Alphabet reported Google Cloud growth of 103%, but earnings missed, capital spending rose to $51.3 billion and free cash flow was negative for a second quarter (−$9.1 billion); it has funded the build-out with $28.7 billion of debt and $12.4 billion of stock sales. Amazon grew AWS 39% but missed on earnings per share and advertising, with trailing free cash flow at −$42.4 billion. Microsoft was the exception: Azure grew 48% with positive free cash flow. Intel fell 28.6%, its worst day since 1974, after a weak outlook. Credit markets noticed: the cost of insuring tech debt hit record highs.
Sector performance

Economy and the Fed
| Release | Actual | Takeaway |
|---|---|---|
| Q3 GDP (annualized) | +3.4% | Above ≈3.1%–3.2% expected |
| Sept. PCE / core PCE | 3.6% / 3.1% y/y | In line to slightly below forecasts |
| Consumer confidence (Oct) | 91.7 | First rise in four months |
| Chicago PMI (Oct) | 55.3 | Softer than expected, still expanding |
| Initial jobless claims | 194,000 | Historically low |
The Fed, led by Chair Kevin Warsh, held at 3.75%–4.00% after September’s hike. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented in favor of another hike, and the statement upgraded growth from “solid” to “strong.” The 10-year yield ended near 4.93% and the VIX rose to 19.42.
Commodities and crypto

- Oil: WTI $104.12; Brent $113.43 (January contract). Hormuz shipping attacks continue.
- Gold and silver: Gold about $3,899 (−2.9% on the week, a one-year low); silver below $50 for the first time in 11 months.
- Bitcoin: about $77,000 after a reported $6.3 billion hack at Binance.
Bitcoin and silver weekly changes are approximate.
Geopolitics
A tanker was hit by limpet mines in the Strait of Hormuz, the first successful strike of its kind since the Iran war began; more than 30 shipping attacks were logged in October. Qatari mediators returned to Tehran with a revised U.S. draft, but the sides disagree on sequencing. Markets are watching for any U.S. action after the November 3 midterm elections.
The week ahead: November 2–6
| Date | Event |
|---|---|
| Mon, Nov 2 | ISM manufacturing; Apple and Palantir report |
| Tue, Nov 3 | U.S. midterm elections; RBA decision; AMD, Pfizer report |
| Wed, Nov 4 | ADP; ISM services; Qualcomm, Arm, Uber report |
| Thu, Nov 5 | Bank of England (hike expected); Airbnb, ConocoPhillips report |
| Fri, Nov 6 | October jobs report (consensus ≈ +55,000 to +60,000; unemployment 4.2%) |
Investment advisory services offered through Foundations Investment Advisors, LLC (“FIA”), an SEC registered investment adviser. FIA’s Darren Leavitt authors this commentary which may include information and statistical data obtained from and/or prepared by third party sources that FIA deems reliable but in no way does FIA guarantee the accuracy or completeness. All such third-party information and statistical data contained herein is subject to change without notice. Nothing herein constitutes legal, tax or investment advice or any recommendation that any security, portfolio of securities, or investment strategy is suitable for any specific person. Personal investment advice can only be rendered after the engagement of FIA for services, execution of required documentation, including receipt of required disclosures. All investments involve risk and past performance is no guarantee of future results. For registration information on FIA, please go to https://adviserinfo.sec.gov/ and search by our firm name or by our CRD #175083. Advisory services are only offered to clients or prospective clients where FIA and its representatives are properly licensed or exempted. Market data is as of the close on October 30, 2026 unless otherwise noted; some figures are approximate or derived. Indexes are unmanaged and cannot be invested in directly.